28 November 2025 Issue 6, 2025 Tim Searle
Digital assets and PPLI
Tim Searle TEP describes why private placement life insurance is a compelling tool for managing digital assets
Although a relatively new concept to wealth advisory firms outside the US, private placement life insurance (PPLI)[1] has been an effective tool for more than 40 years, offering a robust planning platform for high-net-worth (HNW) families. Since most offshore company and trust structures are porous at best nowadays, PPLI has the ability to reinforce legacy structures and planning to meet the constantly changing fiscal and regulatory landscape challenges of today. It returns privacy to families, provides tax deferral, facilitates intergenerational wealth transfer and secures protection for myriad assets, including cash, stocks, private equity, jets, yachts, art, hedge funds and digital assets.
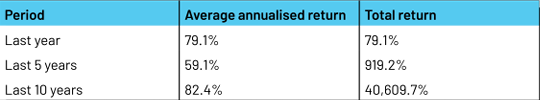
It is widely accepted that digital assets are now the norm in the HNW portfolio. Since its inception in 2009, Bitcoin has experienced unprecedented price appreciation, including an average annual return of 74.1 per cent over the last ten years.[2] Between 2012 and 2025, the Bitcoin index demonstrated a positive annual return in nine of the 13 years (99 per cent), with a total return over the last ten years of 25,480 per cent. While underscoring that past performance is no indication of future returns, the most vocal advocates of Bitcoin believe that its fixed supply of 21 million coins 1 makes it a compelling store of value and an ideal hedge against the debasement of government-issued fiat currencies.
Regardless of the volatility associated with this asset class, proponents of Bitcoin firmly believe that its decentralised nature affords it the purest definition of an asset that provides an effective hedge against the deleterious effects of inflation. Thus, for its advocates, Bitcoin is a form of ‘digitised gold’ with exceptional long-term potential. Combining PPLI and digital assets allows HNW individuals to participate in an asset’s appreciation potential over a longer horizon while mitigating some of the risks associated with direct ownership. PPLI is uniquely positioned as a compelling wealth management solution for tax, asset protection and risk mitigation. Moreover, when PPLI is combined with a properly structured trust, the beneficiaries of the trust can receive a tax-free disbursement of the PPLI’s underlying assets, thereby optimising the intergenerational wealth passed on to the insured’s heirs.
There are multiple jurisdictions for PPLI, and it is important to source the correct one(s) to meet the client’s needs today and for the future, ensuring alignment with the family’s priorities. Tax optimisation is key, and assessing the number of dual- or double-taxation agreements will allow the PPLI to deliver exceptional returns unhampered by income or capital gains. Similarly, the platform can be Shari’acompliant for families seeking a solution in line with their religious beliefs (Murabaha/Wakalah).
Investment gains within the policy grow on a tax-deferred basis, meaning they are not subject to capital gains tax as long as they remain within the policy. Similarly, death benefit proceeds are typically paid tax-free to beneficiaries, providing a significant advantage in estate planning. This deferral can lead to substantial wealth accumulation over time, particularly for investments with high growth potential. Loans can be taken from a PPLI policy, which may be tax-advantageous compared with a distribution, should the need for liquidity arise.
Moreover, credit committees of banks or finance firms have greater comfort lending to insurance companies (the PPLI provider). This is because the structure is robust, domiciled in a recognised and regulated jurisdiction, can deploy loan protection cover and is easy to collapse if needed or in case of default. In addition, PPLI can combine multiple assets within one platform, so there is no need to have one for digital assets and another for more conventional forms of investment. Some PPLI policies are designed to be country-specific, providing bespoke benefits tied to the approval of the tax authorities concerned.
The misconception that digital assets are somehow outside the purview of governmental bodies is diminishing and misguided at best. The very nature of the blockchain is to track every transaction. Within the PPLI structure, the ownership of digital assets can be kept private, providing an additional layer of asset protection and protection against public disclosure. This is particularly important for individuals who value discretion in their financial affairs, especially as digital assets attract enhanced scrutiny and regulatory oversight. This will subside over time, as growing acceptance of digital assets as part of a diversified investment strategy becomes increasingly mainstream.
The process to onboard digital assets is relatively straightforward. Initially, as with all anti-money laundering and know-your-customer procedures, the provenance of the assets requires pre-screening. This screening is possible with a number of blockchains, with associated digital assets held within the client’s wallet.
Each PPLI policy is linked to a dedicated sub-account at the custodian, ensuring transparency and ownership separation. Moreover, as in all asset classes, there is never any contamination of assets between those of the client and the PPLI provider. This gives clients further comfort that their assets do not sit on the balance sheet of the PPLI company, which is not the case with banks.
Once compliance screening is complete, all assets are received directly from clients’ wallets, so there is no need to liquidate – sometimes referred to as in specie transfer. Thereafter, the client can create multi-user approval flows with rolespecific permissions for the initiator, approver, auditor or administrator as part of the design of the PPLI solution. Similarly, the various methods of managing digital assets remain, including staking, option strategies, loans, ‘Hodl’,[3] on/off ramp to fiat and the use of third-party managers.
Combining these options with the aforementioned benefits and distinct beneficiary designation from the outset (changeable as required), PPLI presents a compelling platform from which to effectively manage all assets, not just digital ones. Many 3 digital asset investors have no mechanism for ensuring that assets are passed on in a timely manner and with regulated oversight. Likewise, they cannot ensure that their wishes will be executed privately, tax efficiently and without probate. Some beneficiaries have no idea of the digital assets to which they could be entitled; these assets can be lost to the ether from which they came.
When it comes to digital assets, the traditional offering from HNW advisors is stale and no longer as effective with next-gen consumers who demand innovation. It is clear that major benefits can be attained with PPLI, beyond the digital asset headline of potentially large returns over the long term. Without careful planning and a clear path for intergenerational wealth transfer, a well-intended digital asset portfolio can fall foul to adverse taxation and lack of regulated third-party oversight. For HNW families who value their privacy and seek both tax-deferred growth and the confidence to access this exciting asset class, PPLI can no longer be overlooked in the international wealth-planning arena.
• [1]
PPLI is a form of life insurance policy tailored for high-net-worth individuals that combines investment flexibility with tax-efficient estate planning benefits.
• [2]
Historical performance of the Bitcoin index available at: Curvo, ‘Bitcoin Market Index (USD)’.
• [3]
‘Hodl’ derives from a misspelling of ‘hold’ and refers to buy-and-hold strategies for the use of cryptocurrencies.
Advisors to HNW families, and particularly next-gen clients, must be equipped with the knowledge and correct tools to adapt to modern needs and deliver robust solutions.
The increasing demand for, and acceptance of, digital assets brings additional challenges to those in high-net-worth (HNW) advisory.
Advisors to HNW families, and particularly next-gen clients, must be equipped with the knowledge and correct tools to adapt to modern needs and deliver robust solutions.
Private placement life insurance cannot be overlooked as part of the advisory toolkit, as it enables digital assets to be private, tax-efficient, protected and integral to an overall intergenerational wealth solution.
Tim Searle
Partner at HNWTAX

Dubai | London | Geneva